Navigating the Canadian real estate landscape requires a clear understanding of mortgage rates, central bank policies, and broader economic trends. Whether you are a first-time homebuyer, an investor, or an existing homeowner facing an upcoming mortgage renewal, Canada’s housing rates directly impact your borrowing capacity and long-term financial health.
To make sound financial decisions, it is essential to look beyond headline interest rates and analyze the underlying factors shaping Canada’s housing market.
Fixed vs. Variable Mortgage Rates in Canada
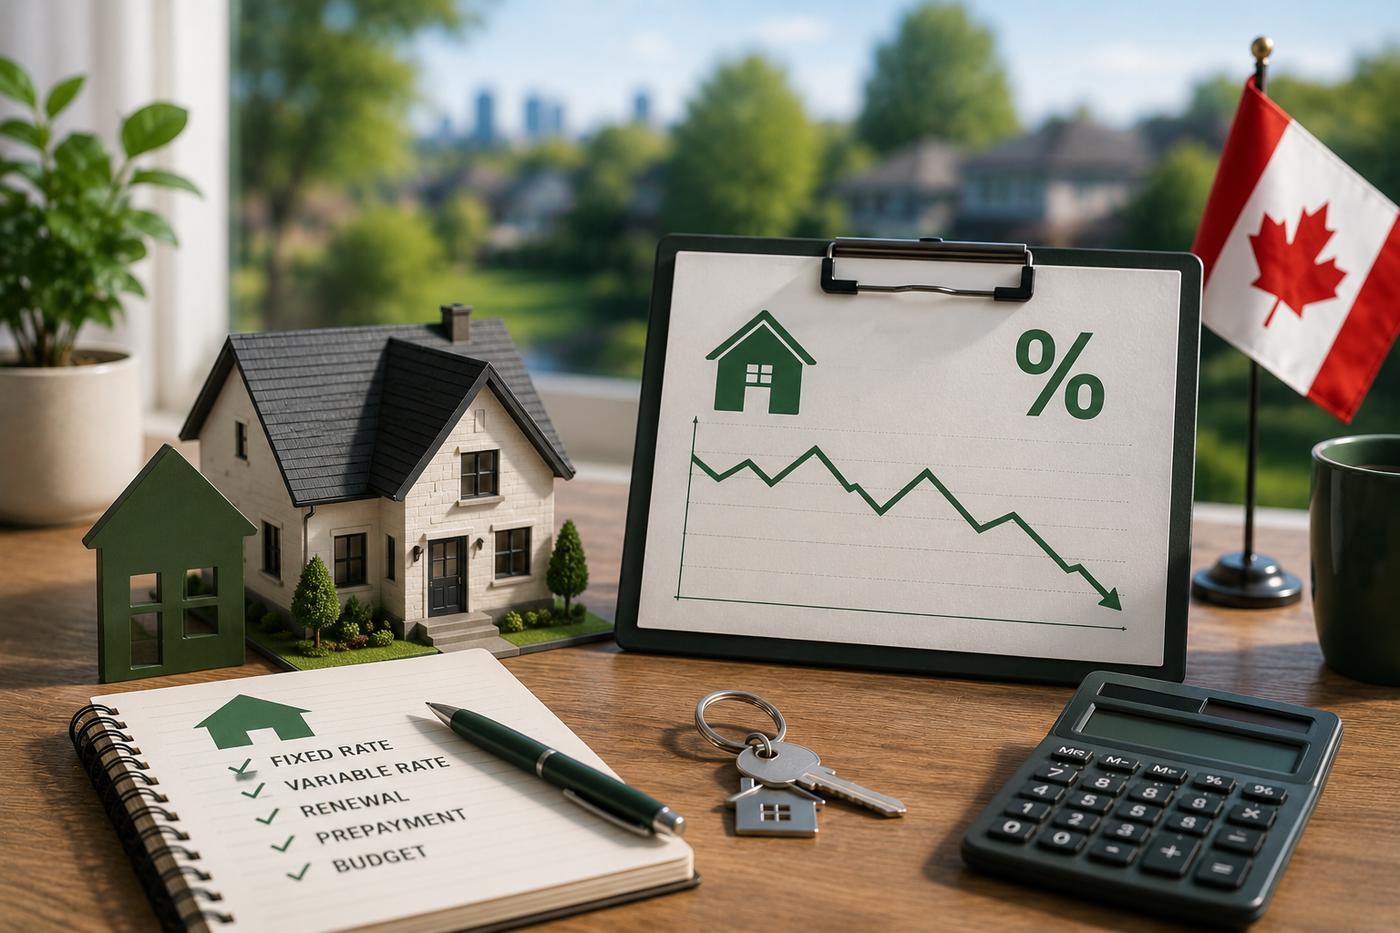
When securing a mortgage in Canada, buyers primarily choose between fixed-rate and variable-rate products. Understanding how each is determined helps in assessing personal risk tolerance and financial strategy.
Fixed-Rate Mortgages
Fixed mortgage rates remain unchanged for the duration of the term, offering budget predictability. These rates are primarily influenced by Government of Canada bond yields, particularly the 5-year bond yield. When bond markets anticipate economic growth or sustained inflation, bond yields rise, leading lenders to increase fixed mortgage rates.
Variable-Rate Mortgages
Variable mortgage rates fluctuate over time based on the lender’s prime rate, which directly follows the Bank of Canada (BoC) policy interest rate. When the BoC adjusts its target rate to stimulate or cool the economy, variable mortgage rates move in tandem.
- Fixed Rate Advantage: Rate lock security, predictable monthly payments, protection against sudden economic shocks.
- Variable Rate Advantage: Potential for savings if benchmark rates decline, typically lower penalty fees for breaking the contract early.
Key Drivers Behind Canadian Housing Rates
Canadian mortgage rates do not operate in a vacuum. Several macro-economic factors influence borrowing costs across the country:
1. Bank of Canada Monetary Policy
The central bank uses its policy rate as a primary lever to control inflation, targeting a 2% midpoint. When inflation rises above target levels, the Bank of Canada often raises interest rates to curb consumer spending, which in turn elevates mortgage borrowing costs.
2. Housing Supply and Demand Imbalances
While interest rates dictate borrowing costs, home prices are heavily driven by supply and demand dynamics. Persistent structural supply shortages in major metropolitan areas keep housing costs elevated, even during periods of higher interest rates.
3. Population Growth and Immigration
Canada’s population growth rate directly fuels demand for both ownership and rental housing. High immigration targets and domestic migration patterns place continuous demand pressure on housing inventory, influencing overall housing affordability.
Regional Breakdown: How Rates Affect Different Canadian Markets
National rate adjustments ripple across provinces differently, largely due to local real estate valuations and economic conditions.
- Ontario and British Columbia: Higher average home prices in cities like Toronto and Vancouver mean buyers carry larger loan balances. Consequently, these markets are highly sensitive to even minor interest rate shifts.
- Alberta and the Prairies: Lower relative home prices provide greater affordability cushions. Regions like Calgary and Edmonton often see increased interprovincial migration when high borrowing costs push buyers out of Ontario and B.C.
- Atlantic Canada: Following significant price increases during recent years, Atlantic markets have stabilized. Buyers in these provinces focus closely on entry-level affordability as local wage growth balances against housing costs.
The Impact of the Canadian Mortgage Stress Test
All federally regulated financial institutions in Canada must apply the Minimum Qualifying Rate, commonly known as the “mortgage stress test.” Homebuyers must prove they can qualify for a mortgage at either:
- The contract interest rate offered by the lender plus 2%, OR
- 5.25%, whichever is higher.
When interest rates rise, the stress test benchmark increases as well. This reduces overall borrowing capacity, requiring buyers to either increase their down payment, adjust their target purchase price, or reduce existing debt liabilities prior to applying.
Actionable Strategies for Navigating Current Housing Rates
To navigate changing interest rates effectively, buyers and homeowners should consider the following steps:
- Secure a Rate Hold: Most mortgage lenders allow you to lock in a fixed rate for 90 to 120 days while shopping for a home, protecting you against rate spikes during your search.
- Explore Hybrid or Shorter-Term Options: If long-term fixed rates seem elevated and variable rates carry too much volatility, a 2-year or 3-year fixed mortgage offers a middle ground, allowing for renewal sooner if market conditions improve.
- Work with Independent Mortgage Professionals: Comparing rates across major banks, credit unions, and mono-line lenders ensures access to competitive pricing and tailored contract terms.
- Stress Test Your Own Household Budget: Calculate your monthly obligations assuming potential rate increases at your next renewal date to ensure your housing costs remain manageable long-term.
Conclusion
Canada’s housing rates reflect a complex dynamic between central bank policy, global economic shifts, and localized real estate market conditions. While interest rate fluctuations are beyond individual control, staying informed, maintaining financial flexibility, and carefully evaluating mortgage structures will help you successfully navigate the Canadian property market.